NetBenefits - Fidelity at Work

Screenshots
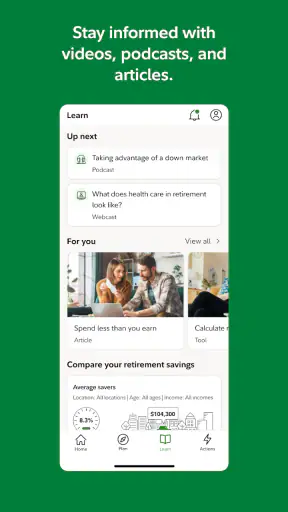
Details
- Rating
- 7.83K reviews
- Version
- 4.35.2
- Developer
- Fidelity Investments
Analysis by Norviv
Managing a workplace retirement account is rarely something I want to turn into a long desktop session. I usually need a quick answer: how much is saved, whether a contribution went through, or what my balance looks like before making another financial decision. NetBenefits - Fidelity at Work is built for that kind of check-in, focusing on Fidelity workplace accounts rather than trying to become an all-purpose personal finance dashboard.
After spending time with the app, my impression is that its strongest quality is focus. It puts employer-linked benefits and retirement information in a mobile setting, which is useful when the account is connected to a job and I do not want to search through an employer portal every time. It is a free finance app from Fidelity Investments, rated for Everyone, and it has been available since 2013. Its current version is 4.35.2 and it requires at least iOS 12, making it accessible on a wide range of supported Apple devices.
The important question is not whether it replaces every financial tool on a phone. It does not. The better question is whether it makes workplace-account tasks easier to complete from start to finish. For employees who already use Fidelity for a workplace plan, the answer is often yes, although the experience still depends heavily on the employer arrangement and on how much financial detail the user expects from a mobile app.
From a quick concern to a useful account check
When a small account question interrupts my day, I want to check the relevant detail without turning it into a full financial review. I’ll look at how NetBenefits fits that quick-check habit, and why the most useful visit often begins with a specific question rather than a general urge to refresh the balance.
Starting with the situation that brings you in
A realistic use case is checking an account after receiving a pay statement. I might notice that my retirement contribution looks different, wonder whether the employer contribution appeared, or simply want to see whether the account value changed. Opening a general banking app would not answer those questions, and a budgeting app may only show an external balance after a delay. NetBenefits is aimed at the account itself, so the starting point is more direct.
The first useful habit is to decide what I actually need before opening it. If I only want a balance or recent account activity, a short visit makes sense. If I am trying to understand investment choices, contribution settings, or workplace benefits in depth, I need more time and should not treat a quick glance as a complete financial review. That distinction prevents the app from being judged unfairly for not behaving like a full adviser or a detailed desktop research platform.
Fidelity’s workplace focus is also its main boundary. The app is most relevant when an employer plan is administered through Fidelity. Someone looking for a single screen that combines unrelated bank accounts, credit cards, household bills, and investments may find a general finance app more suitable. NetBenefits is better understood as a front door to workplace benefits, not a universal money organizer.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
Signing in and locating the right account
The handoff from the phone to the account is the first point where convenience meets security. I want the sign-in process to feel familiar, but I also expect extra care because the app exposes retirement and employment-related information. Once inside, the key task is identifying the correct workplace account rather than assuming every displayed figure belongs to the same plan.
This matters for people who have changed employers, hold more than one workplace plan, or use Fidelity for several benefit arrangements. A balance can look simple while the underlying account context is not. My practical advice is to pause at the account-selection stage and confirm the employer or plan name before interpreting a number. That small check is more valuable than rushing straight to the largest figure on the screen.
Users should also expect the mobile experience to reflect the account relationship already established with Fidelity and the employer. The app cannot make an unrelated workplace plan appear as a Fidelity plan, and it cannot remove the administrative steps that belong to enrollment or payroll. When something looks incomplete, the problem may sit with the account setup or payroll handoff rather than with the phone interface itself.
Moving from the overview to the detail
Once I reach the account overview, I use it as a starting point rather than a final conclusion. The balance answers “how much is there now,” but it does not automatically answer “why did it change” or “what should I do next.” I look for the surrounding context: recent activity, contribution information, and the relationship between the current value and my own expectations.
This is where the app can save time. A mobile overview is useful when I am standing in line, commuting, or reviewing finances after payday. I can make the first observation without opening a laptop. The trade-off is that a phone screen encourages quick interpretation. Retirement values move, contributions may arrive on a schedule, and a single day’s change should not be mistaken for a meaningful long-term result.
A less obvious but important workflow is to compare the app’s information with the pay statement or employer benefits material when something seems off. If the contribution on the statement does not appear immediately in the account, I would not assume the money is missing. Payroll processing and account posting can involve a handoff between systems. The app is useful for checking the destination, but it may not explain every timing difference on its own.
Using the information to make a decision
The outcome I want from a visit is usually a next action: leave the contribution settings alone, investigate a discrepancy, review an investment choice, or contact the appropriate support channel. NetBenefits works best when I treat it as a decision aid for workplace-account maintenance rather than as a source of instant financial certainty.
For example, if my goal is to increase retirement savings, I first confirm the current contribution arrangement and then consider whether the change belongs in the app, with my employer, or through payroll. That distinction is easy to miss. A mobile account view can show the result of a payroll decision, but the employer’s process may control when a new instruction takes effect. Checking the app is therefore one step in the workflow, not always the place where the entire workflow begins or ends.
I also find it useful to separate facts from reactions. Seeing a lower investment value can be uncomfortable, but the app cannot turn a short-term movement into a reliable forecast. The responsible use is to gather the account information, review the available plan materials, and make changes only when I understand what they affect. That is a more realistic benefit than expecting the app to tell me exactly what investment decision to make.
The handoffs that shape the experience
Workplace finance involves several parties: the employee, the employer, payroll, Fidelity, and sometimes an investment or benefits administrator. NetBenefits sits in the middle of that chain. It gives me a convenient view of information associated with the Fidelity workplace account, but it does not control every upstream or downstream event.
This becomes clear in everyday situations. Suppose I change jobs and want to check an old workplace account while learning about a new one. The app may be helpful for revisiting Fidelity-managed information, but the new employer’s enrollment process remains separate. Likewise, if a contribution amount is wrong, the app may help me verify the account record, while payroll or human resources may be the right place to correct the source instruction.
That separation is not a flaw unique to this app, but it is a friction point users should understand before relying on it. I would use the app to gather precise account context before contacting anyone. Having the relevant plan visible can make a support conversation more efficient than describing the issue from memory.
Another practical handoff occurs when I move from a quick mobile check to a more involved review. The phone is convenient for monitoring, but complex comparisons, lengthy educational material, or careful retirement planning may be easier on a larger screen. I do not see that as a reason to dismiss the app. It simply means the mobile version is one part of a broader process.
What a successful visit looks like
A successful session ends with clarity, not necessarily with a transaction. I know which workplace account I viewed, whether the recent information matches my expectation, and what the next step is if it does not. That may sound modest, but it is exactly the kind of outcome a workplace-account app should deliver well.
The app’s scale suggests that this focused approach resonates with many people. It has more than a million installs, an average rating of 4.0, and around twenty-five thousand ratings. Those figures do not guarantee that every user will have a smooth experience, but they indicate that the app is established enough to be a familiar option for Fidelity workplace customers.
I would not use the rating as a substitute for my own needs. A person who mainly wants quick account visibility may be satisfied, while someone expecting sophisticated planning tools may rate the same experience differently. The app’s value depends on whether its workplace-account focus matches the question I am trying to answer.
Where the flow breaks
The first break is expectation. If I open NetBenefits expecting a complete household financial picture, I am starting with the wrong tool. It is not the natural choice for tracking grocery spending, splitting bills, or viewing every financial institution in one place. A budgeting app or a bank’s aggregation feature may be better for those jobs.
The second break is interpretation. Retirement balances are not ordinary checking-account balances. A number can change because of contributions, market movement, fees, or timing, and a mobile snapshot may not provide enough explanation for a confident conclusion. I appreciate quick visibility, but I would not make a major change solely because one screen looks different from the last time I checked.
The third break is administrative. When an employer changes plan arrangements, when payroll information is delayed, or when a former employee is trying to understand an older account, the app may expose the situation without resolving it. That can feel frustrating because the information is visible but the corrective action belongs elsewhere. In those moments, the best use of the app is documentation: confirm what is shown, note the relevant account context, and then follow up with the employer or Fidelity through the appropriate route.
There is also a usability trade-off in mobile finance. Convenience encourages frequent checking, but frequent checking can encourage emotional reactions to short-term investment movement. I recommend using the app for purposeful reviews rather than repeatedly refreshing the balance. Its strength is access, not prediction.
Who should choose it, and who should skip it
I would recommend NetBenefits to an employee whose workplace account is handled through Fidelity and who wants a practical way to check retirement or related workplace information away from a computer. It is especially useful for confirming account status after payroll, preparing for a benefits conversation, or keeping an eye on several employer-linked details without navigating a desktop site every time.
It is also a reasonable choice for someone who prefers to separate workplace savings from everyday spending. That separation can make retirement information easier to focus on, provided the user understands that the app is not a complete financial plan. The free price removes a common barrier to trying it, and the Everyone age rating makes its basic audience broad, although the usefulness still depends on having the relevant Fidelity workplace relationship.
I would suggest skipping it as a primary finance app if the main goal is household budgeting, account aggregation across unrelated providers, or detailed investment research. In those cases, a dedicated budgeting service, a brokerage platform designed for broader investing, or a desktop planning workflow may provide a better fit. NetBenefits can still be a companion for the Fidelity workplace account, but it should not be forced to replace tools designed for those other purposes.
My practical routine for getting more from it
My preferred routine is simple. I open the app with one question, confirm the account identity, check the relevant detail, and write down the next action if anything needs follow-up. I avoid treating the displayed balance as a complete performance report, and I compare unusual changes with payroll records or plan information before contacting support.
For a contribution question, I would check the pay statement first, then use the app to see whether the account reflects the expected activity. For a job change, I would verify which employer account I am viewing before assuming that a missing plan is an error. For an investment concern, I would use the app to observe the account and then move to fuller plan information before changing anything. These small workflow choices reduce confusion and make the mobile access genuinely useful.
I also recommend keeping the app’s role clear when discussing finances with a partner or adviser. The screen can provide a current reference point, but retirement decisions often require details that are easy to overlook in a compact mobile view. Sharing the exact account context and the reason for a change is more helpful than sending a balance without explanation.
Final assessment after following the full workflow
NetBenefits - Fidelity at Work succeeds when the journey is narrow and concrete: I need to reach a Fidelity workplace account, inspect what is there, and decide whether a follow-up is necessary. The app makes that journey more convenient than relying on a desktop-only routine, and its long availability, free access, and broad adoption make it an easy option for eligible users to try.
Its limitations are just as important. It does not eliminate employer and payroll handoffs, it cannot turn a changing retirement balance into a simple answer, and it is not the right replacement for budgeting or comprehensive financial planning tools. The best experience comes from using it as a reliable mobile checkpoint rather than expecting it to manage every part of personal finance.
My overall opinion is positive but specific: this is a practical workplace-account companion, not an all-purpose money app. If Fidelity manages the account connected to your job, I would keep it available for purposeful checks and follow-up preparation. If your financial life extends far beyond that workplace relationship, pair it with a tool designed for the rest rather than asking it to do a job it was never meant to handle.
Frequently Asked Questions
01What is NetBenefits - Fidelity at Work used for?
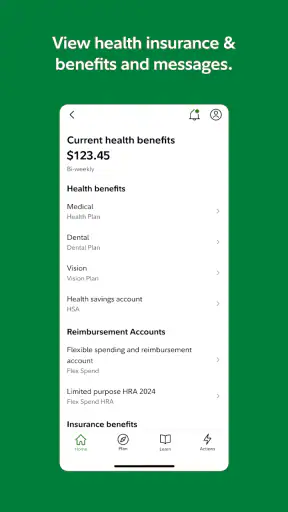
NetBenefits - Fidelity at Work is designed to help eligible employees manage workplace benefit accounts through Fidelity. Depending on your employer’s plan, the app may let you review retirement savings, check balances and transactions, monitor investments, view contribution details, access statements, and manage certain benefits. Available tools can differ significantly between employers and plan types.
02Can anyone download and use NetBenefits - Fidelity at Work?
Anyone may be able to download the app, but access to its account features generally requires an eligible Fidelity workplace account and valid login credentials. Your employer must offer a participating plan supported by Fidelity. If you are unsure whether your account qualifies, check your employer’s benefits portal or contact Fidelity workplace support before attempting to register.
03What information and features can I access in the app?
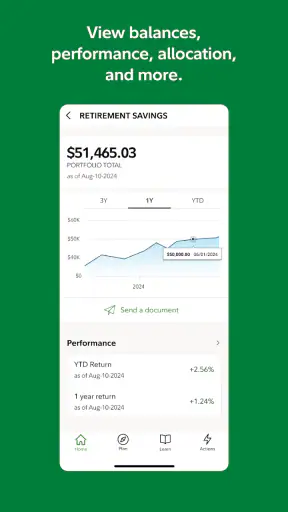
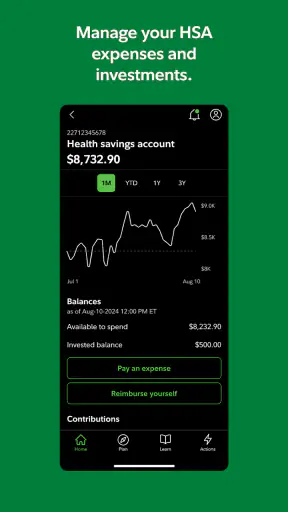
The information displayed depends on the plans connected to your Fidelity profile. Common features include viewing retirement account balances, contribution rates, investment allocations, recent activity, performance information, and plan documents. Some users may also access health savings or other workplace benefits. Not every employer enables every feature, so the app may look different from one account to another.
04Is NetBenefits - Fidelity at Work secure?
The app is intended to protect workplace-benefit information using account authentication and security controls provided by Fidelity. Users should still take precautions by downloading it only from an official app store, keeping the app and device updated, using a strong unique password, and enabling available security options such as biometric sign-in or multi-factor authentication. Never share verification codes or login details.
05Can I make changes to my retirement plan through the app?
In many cases, eligible users can perform certain actions directly in NetBenefits, such as changing contribution percentages, reviewing investment choices, adjusting allocations, or accessing plan-specific tools. However, available actions depend on your employer’s plan rules and account status. Before confirming a change, review any fees, restrictions, tax implications, or processing delays that may apply.


